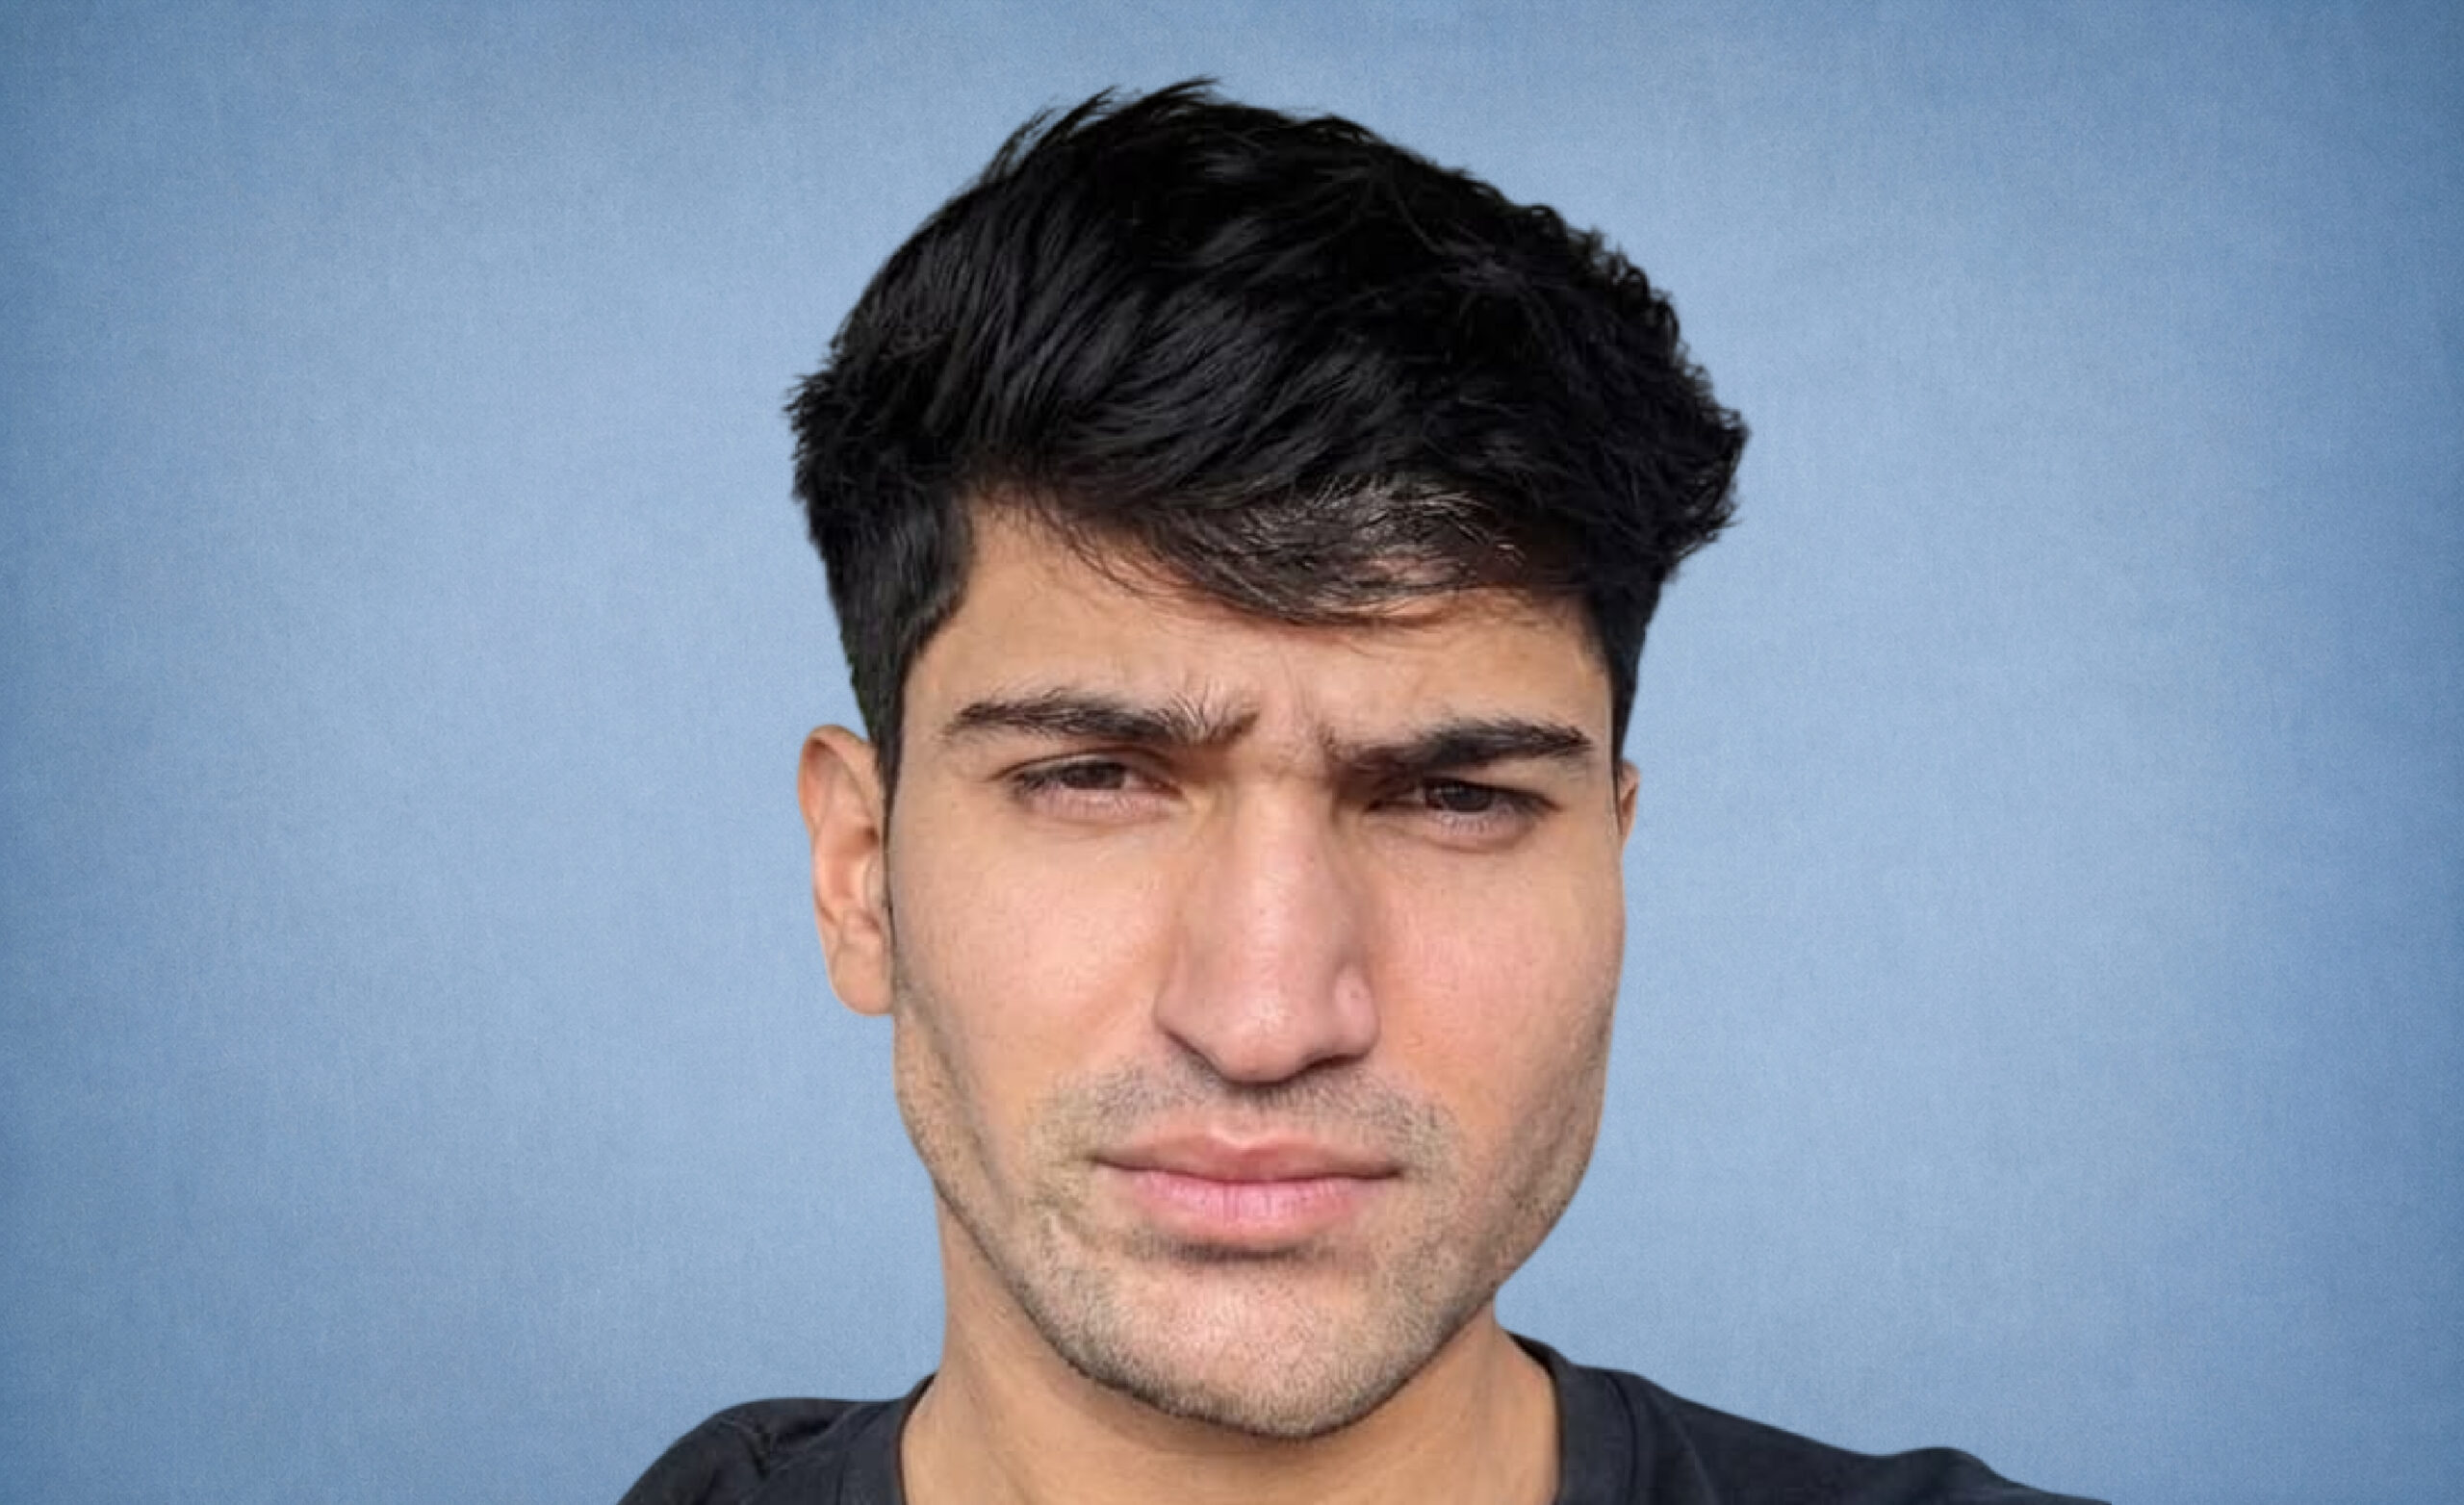
As agriculture enters the digital age, empowering farmers requires more than technology alone; it demands inclusive financial infrastructure. In this conversation, Ali Abdul Ghaffar shares how ZaraatPay is transforming agricultural finance through data-driven credit, transparent marketplaces, and sustainable innovation, strengthening both farmer prosperity and Pakistan’s long-term food security.
Boardroom: What inspired the creation of ZaraatPay?
Ali Abdul Ghaffar: It started with a simple observation that didn’t sit right with me: Pakistan’s agricultural sector produces roughly a quarter of the country’s GDP, yet the people actually growing the food are among the poorest in the economy. That gap isn’t natural, it’s structural. Farmers were borrowing from moneylenders at 24 to 36 percent interest per season because no bank would lend to them. They were selling their harvest for a fraction of its retail value because they had no way to know what it was really worth. Subsidies meant for them were being intercepted before they ever reached the field. What made it more than an economic concern for me was realizing this is also a food security and national security issue. When wheat production drops 11 percent in a single year and the country ends up spending over a billion dollars importing wheat while its own farmers are selling below cost, that’s not a distant policy failure, that’s a country becoming dependent on outside markets to feed itself. A nation that cannot reliably feed its own population is vulnerable in ways that go far beyond economics. Once I started researching this properly, I realized the problem wasn’t a lack of goodwill or a lack of money in the system. It was a lack of infrastructure that actually served the farmer instead of extracting from them. ZaraatPay grew out of the conviction that this infrastructure could be built, and that building it was as much about securing the country’s food supply as it was about helping individual farmers.
Boardroom: Why did you choose smallholder farmers as your primary focus?
Ali Abdul Ghaffar: Smallholder farmers are where the exclusion is most severe and where the impact is most direct. Large landholders already have access to formal credit and negotiating power in the market. It’s the 8.5 million smallholder and landless farmers who have neither. They’re the ones without land titles to offer as collateral, without banking history, without leverage when they sell their harvest. If I built something that only served farmers who were already reasonably well off, I wouldn’t be solving the actual problem, I’d just be adding another layer on top of an already functioning system. There’s also a national interest dimension to this that I think gets overlooked. Smallholders collectively farm the majority of Pakistan’s cultivated land and produce a huge share of its staple crops. If that base of producers is undercapitalized, indebted, and unable to invest in better yields, the country’s food security rests on an unstable foundation. Strengthening smallholders isn’t just an equity issue, it’s the most direct way to strengthen the resilience of the entire national food supply. Smallholders are also, frankly, where the numbers work: they’re the majority of Pakistan’s farming population, so serving them properly means serving the backbone of the sector.
Boardroom: How does ZaraatPay redefine financial inclusion for rural communities?
Ali Abdul Ghaffar: Most conversations about financial inclusion focus on access, opening a bank account, having a mobile wallet. That’s a start, but it’s not inclusion if the products available still require collateral a farmer doesn’t have. Real inclusion means redesigning the underwriting itself. ZaraatPay doesn’t ask a farmer to prove they own land. It looks at what they actually do: their production history, their repayment behavior, their engagement with the marketplace. That’s a fundamentally different starting point. It means a landless sharecropper, someone who has never qualified for a loan from any institution in this country, can build a credit profile and graduate into larger and cheaper credit over time. And I’d argue that’s inclusion with a purpose beyond the individual farmer. A farmer who can access credit at 14 percent instead of borrowing at 30 percent from an informal lender can afford better seed, better inputs, and can actually invest in yield instead of just surviving the season. Multiply that across millions of farmers and you’re not just improving household income, you’re improving national output and food
security at the same time. That’s inclusion that follows the farmer, not the farmer trying to fit into a system that was never built for them.
Boardroom: What differentiates your credit model from conventional agricultural lending?
Ali Abdul Ghaffar: Conventional lending in Pakistan, formal or informal, is collateral-first. If you don’t own land, you don’t qualify, full stop. Our model flips that. We run two parallel scoring systems: one for land-owning farmers that still uses agronomic and behavioral data alongside land value, and a separate one for landless and sharecropping farmers that uses the sharecrop agreement itself as the basis for trust, combined with repayment history and market activity. Both are dynamic. A farmer’s credit limit and interest rate improve as their track record on the platform grows, the same way your credit score improves anywhere else in the world. That’s simply not how agricultural lending has worked here. It’s also automated, so a farmer isn’t waiting weeks for a loan officer to manually evaluate an application that a computer can score more fairly and more consistently.
Boardroom: How does technology improve transparency across the agricultural value chain?
Ali Abdul Ghaffar: Opacity is where most of the extraction happens. A farmer who doesn’t know the real mandi price for wheat that day is negotiating blind, and the buyer knows it. Technology fixes that in the simplest way possible: it gives farmers the same information everyone else already has. Real-time pricing pulled directly from government market data sources means a farmer walks into a negotiation knowing exactly what their crop is worth. Beyond pricing, technology also creates a permanent, verifiable record, of transactions, of repayments, of input purchases, of yields. That record is what allows trust to be built without requiring a personal relationship with a moneylender who has every incentive to keep that information asymmetric. Transparency isn’t a nice feature here; it’s the mechanism that breaks dependency.
Boardroom: What challenges have you faced in replacing informal farming ecosystems?
Ali Abdul Ghaffar: The biggest challenge isn’t technical, it’s trust. Informal lenders and commission agents have relationships with farmers that go back generations. Those relationships come with real value, they show up in person, they know the family, they’ve been there during a bad harvest. You can’t out-code that overnight. We’ve had to build our own trust the slow way, through field agents who work directly in these communities, through partnerships with the same local networks rather than trying to bulldoze past them, and by proving reliability one repaid loan and one fair transaction at a time. There’s also the practical reality of connectivity and digital literacy in rural areas, and the regulatory path required to move money legally and safely. None of these are solved by ambition alone. They’re solved by showing up consistently and letting results speak.
Boardroom: How do carbon credits create new economic opportunities for farmers?
Ali Abdul Ghaffar: For most farmers, the environmental cost of chemical-heavy farming, and the environmental benefit of avoiding it, has never shown up on their balance sheet. Carbon credits change that. When a farmer adopts organic inputs or permaculture practices that build soil carbon, that’s no longer just a good deed with no financial return, it becomes a verifiable, sellable asset. We use blockchain-based tracking to record that sequestration and connect it to real carbon markets, which means a farmer practicing regenerative agriculture can earn meaningful additional income, in some cases tens of thousands of rupees a year, simply for farming in a way that’s better for the land and for the water supply downstream. It aligns what’s good for the planet with what’s good for the farmer’s income, which is the only way sustainable practices actually scale.
Boardroom: What policy changes could accelerate digital agriculture in Pakistan?
Ali Abdul Ghaffar: A few stand out clearly. First, faster and clearer pathways for fintechs to obtain payment licensing or partner formally with licensed institutions, the current process is slow enough that it discourages innovation in exactly the sector that needs it most. Second, redirecting a portion of existing chemical fertilizer subsidies toward organic input support, which would correct a market distortion that’s been pushing farmers toward harmful practices for decades. Third, official recognition and infrastructure for agricultural carbon markets, so platforms like ours aren’t building that verification layer entirely from scratch. Fourth, expanding open access to government market-price data through proper APIs rather than static reports, since real-time price transparency is one of the simplest, cheapest interventions with an outsized impact on farmer income. And I’d add a fifth, treating agricultural digitization as a food security and national security priority in its own right, not just an economic nice-to-have. When a government is spending over a billion dollars importing wheat in a year its own farmers underproduced, that should be treated with the same urgency as any other supply chain vulnerability.
Policy that speeds up digital agriculture is, in effect, policy that reduces the country’s exposure to global food price shocks and import dependency.
Boardroom: How do you measure success beyond financial performance?
Ali Abdul Ghaffar: Financial metrics tell you whether the model is sustainable, but they don’t tell you whether it’s actually changing someone’s life. So, we look closely at repayment rates, not just because they matter for the business, but because a high repayment rate means we scored that farmer correctly and gave them a loan they could genuinely use and repay, which is itself a signal of dignity restored rather than debt imposed. We look at whether farmers graduate from smaller landless credit products into larger ones over time, because that’s evidence of real upward mobility. We look at how much of the retail price a farmer is capturing through the marketplace compared to selling through a middleman. And increasingly, we look at environmental indicators, soil health, water contamination avoided, carbon sequestered, because those outcomes are just as real as revenue, even if they take longer to show up on a spreadsheet.
Boardroom: What is your long-term vision for ZaraatPay and the sector?
Ali Abdul Ghaffar: I want ZaraatPay to become infrastructure that Pakistani agriculture simply runs on, the way mobile money became infrastructure in parts of East Africa. Not product farmers occasionally use, but the default way credit, market access, and sustainable farming income work in this country. Longer term, that means expanding beyond Punjab into every province, deepening the carbon marketplace so environmental stewardship is a normal and expected source of farm income rather than a niche one, and building enough of a repayment and production track record that our farmers can eventually access even cheaper capital from banks and development institutions on the strength of data we’ve built together. But beyond the company itself, my vision is for agriculture to be treated, and to function, as a pillar of national security in Pakistan, not just a line item in the GDP breakdown. A country that can reliably feed itself, without depending on emergency wheat imports or watching its farmers go under after a bad season, is a more stable and more sovereign country. If ZaraatPay plays even a part in getting Pakistan closer to that kind of food security, built farmer by farmer rather than announced in a policy paper, then we’ll have done something that matters well beyond the balance sheet. The bigger vision is that a farmer’s own work, not their land title, not their family connections, becomes the thing that unlocks opportunity. If we get that right, we’re not just building a company, we’re rebuilding how an entire sector treats the people who feed it, and strengthening the food security of the country in the process.